GCC financing gap exceeds US$ 250bn
Private credit is emerging as an increasingly important source of financing across the GCC, as businesses and asset owners seek more flexible capital structures and the region faces a financing gap estimated at more than AED 918bn (US$ 250bn).
While real estate remains an important area of deployment, opportunities are expanding across sectors including technology, SME lending, education, healthcare, logistics and supply chain, as businesses seek alternative sources of growth and expansion capital.
The GCC and Egypt private credit market is projected to grow by approximately 15–30 percent annually, potentially reaching between AED 40.4bn and AED 73.5bn (US$ 11b–US$ 20bn) by the end of the decade, highlighting the growing role of alternative financing across the region.
Financing solutions
This momentum comes as the UAE real estate market continues to expand and developers increasingly require financing solutions beyond traditional bank lending, particularly for acquisitions, bridge financing, project completion and recapitalisation.
Dubai’s property sector delivered a record performance in 2025, with real estate investment exceeding AED 680bn (US$ 185.2bn) across more than 258,000 deals, demonstrating the significant scale of capital flowing into the sector and the growing need for diversified financing solutions.
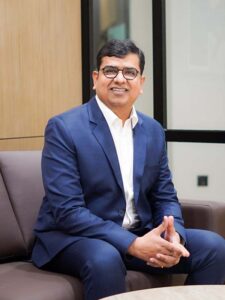
Amit Jhunjhunwala, Chief Investment Officer, UAE, Nisus Finance, said private credit should be viewed as complementary to traditional banking rather than as a replacement. “Private credit is not replacing banks. It is completing a capital structure that has traditionally had a gap between what a deposit-taking institution can prudently lend against and what a business or asset actually requires to grow, develop or complete a transaction,” he continued.
Structural rather than cyclical
He added that this financing need is structural rather than cyclical. Prudential requirements naturally limit the types of financing banks can provide, creating a long-term role for private credit alongside traditional lenders. This can be particularly relevant for growing SMEs and businesses in sectors where financing requirements may not always fit conventional lending structures or timelines.
The UAE is particularly well placed to participate in the next phase of private credit growth, supported by established financial centres including the Dubai International Financial Centre (DIFC) and Abu Dhabi Global Market (ADGM).
Regulatory frameworks
Their regulatory frameworks, established fund structures and enforcement mechanisms have helped create an environment in which international institutional capital can evaluate and underwrite UAE opportunities.
The development of Abu Dhabi as a regional private credit centre is also strengthening the sector. Mubadala’s private credit portfolio had reached approximately AED 73.5bn (US$ 20bn) by early 2025, according to figures cited in the analysis.
Over the next three to five years, private credit activity in the region is expected to broaden across several areas of the economy. In real estate, opportunities are expected around residential completion and last-mile financing, acquisition and bridge financing, and recapitalisation. Beyond property, technology and growth-stage businesses, SME lending, education and healthcare, logistics and supply chain are also expected to create opportunities for flexible and structured capital.
Capital-intensive sectors including data centres and digital infrastructure, logistics and warehousing, healthcare infrastructure and hospitality could also become increasingly important areas for structured lending as investment and expansion continue across the region. Jhunjhunwala added that the growing investment relationship between India and the GCC could create further opportunities for cross-border private credit.